
For eligible homeowners
Cash-Out 90
Explore financing above the usual 80% cash-out threshold, up to a maximum 89.99% LTV.
Your new mortgage can total up to 89.99% of your home’s appraised value—also called loan-to-value, or LTV. Eligible homeowners pay no mortgage insurance.
Available in all states except Texas.
Subject to lender requirements.
89.99% is the total new loan-to-value ratio—not the cash you receive. Existing liens, closing costs, loan limits and underwriting affect proceeds. Refinancing replaces your current mortgage and may increase its rate, payment and total cost.
Tell Ethan what you have in mind.
A personal reply from Ethan
Ethan will review your inquiry and contact you personally to discuss your goals and possible next steps.
Schedule a call with EthanOptional · 20-minute phone call · Opens Google Calendar
Mortgage experience
AZ · CA · IN · OH · TX
Talk directly with Ethan
THE EXPERIENCE, IN THEIR WORDS
A new home. A refinance. A clear next step.
Hear from clients who have worked with Ethan.
FEATURED REFINANCE CLIENT
Review summary Briana describes honest guidance and responsive communication during her refinance.
Refinance client experienceMORE CLIENT EXPERIENCES
REPEAT CLIENT
“Ethan is attentive, straight to the point, knows his stuff and works fast.”
PERSONAL ATTENTION
“He was very attentive and on the ball.”
YOUR HOME. YOUR NEXT STEP.
Before replacing your mortgage, compare the cash available, closing costs and long-term impact.
Discuss my situationExcerpts and separately labeled summaries describe individual experiences, not guaranteed outcomes or results under this cash-out program. Ratings are separate platform snapshots, not a combined count of unique clients.
MORE THAN ONE WAY TO USE YOUR EQUITY
Accessing more equity can be useful—but only when the numbers and tradeoffs make sense. Start with what you want to accomplish.
For eligible homeowners
Explore financing above the usual 80% cash-out threshold, up to a maximum 89.99% LTV.

For a clearer comparison
Compare a mortgage refinance with your existing debts—not just the monthly payment, but the total cost.

For the home you have
Review whether using home equity is an appropriate way to fund your planned improvements.

For your current mortgage
Have a low first-mortgage rate? Compare keeping it with other potential ways to access equity.
Program eligibility, availability, documentation, and terms vary by lender and state. Not all applicants will qualify. This is not a commitment to lend.
A STARTING POINT, NOT AN APPROVAL
Primary residenceFor eligible primary residences in Arizona, California, Indiana and Ohio, subject to lender review. Not available in Texas.
680+ credit scorePublished minimum; credit, income and the full loan file still require review.
Conforming loan limitsYour property, appraisal and available loan amount affect eligibility and proceeds.
Individual underwritingDocumentation, mortgage history and lender requirements apply.
30-year fixed only. Maximum DTI is determined by DU/LPA and cannot exceed 50%. UWM lists six months of seasoning when paying off a first-lien mortgage; additional requirements may apply. Product information checked November 7, 2026. Availability and requirements may change. Published program overview ↗
PUT THE DIFFERENCE IN PERSPECTIVE
Compare an 80% loan-to-value illustration with Cash-Out 90’s 89.99% maximum. Cash-Out 90 is not available in Texas; this comparison does not apply there. This is a starting point—not an offer or an approval.
Illustrative loan cap: $847,440 (UWM’s early estimated 2027 one-unit limit). This is not the official FHFA 2027 limit. Confirm the applicable Cash-Out 90 limit and eligibility with the lender.
80% LTV COMPARISON
$310,000Illustrative proceeds before costsUP TO 89.99% LTV
$397,440Illustrative proceeds before costsMinus closing costs and prepaid items. Mortgage balances are already subtracted. The $847,440 illustrative loan cap limits these amounts.
Review my actual optionsIllustration for an eligible one-unit primary residence in Arizona, California, Indiana or Ohio, subject to lender confirmation. Not applicable to Texas; Cash-Out 90 is not available there. New loan = the lesser of home value × LTV or $847,440; proceeds shown = new loan minus entered mortgage balances, floored at $0. Closing costs and prepaid items must still be subtracted. A $0 result may mean additional cash is required. Appraised value, lender limits, income, credit, other liens and underwriting can change the result. The specialty program’s LTV range is 80.01%–89.99%. No rate, payment, savings or approval is promised. UWM early-limit announcement ↗
THE TEAM PIKOFF APPROACH
You don’t need to have every answer before we talk. You just need a starting point.
Find my starting pointWhat would you like to accomplish with your equity? Start with the amount and purpose—not a promised approval.
Compare your existing mortgage, income, property value, costs and potential cash-out options.
When you’re ready, continue through Barrett’s secure application and underwriting process.
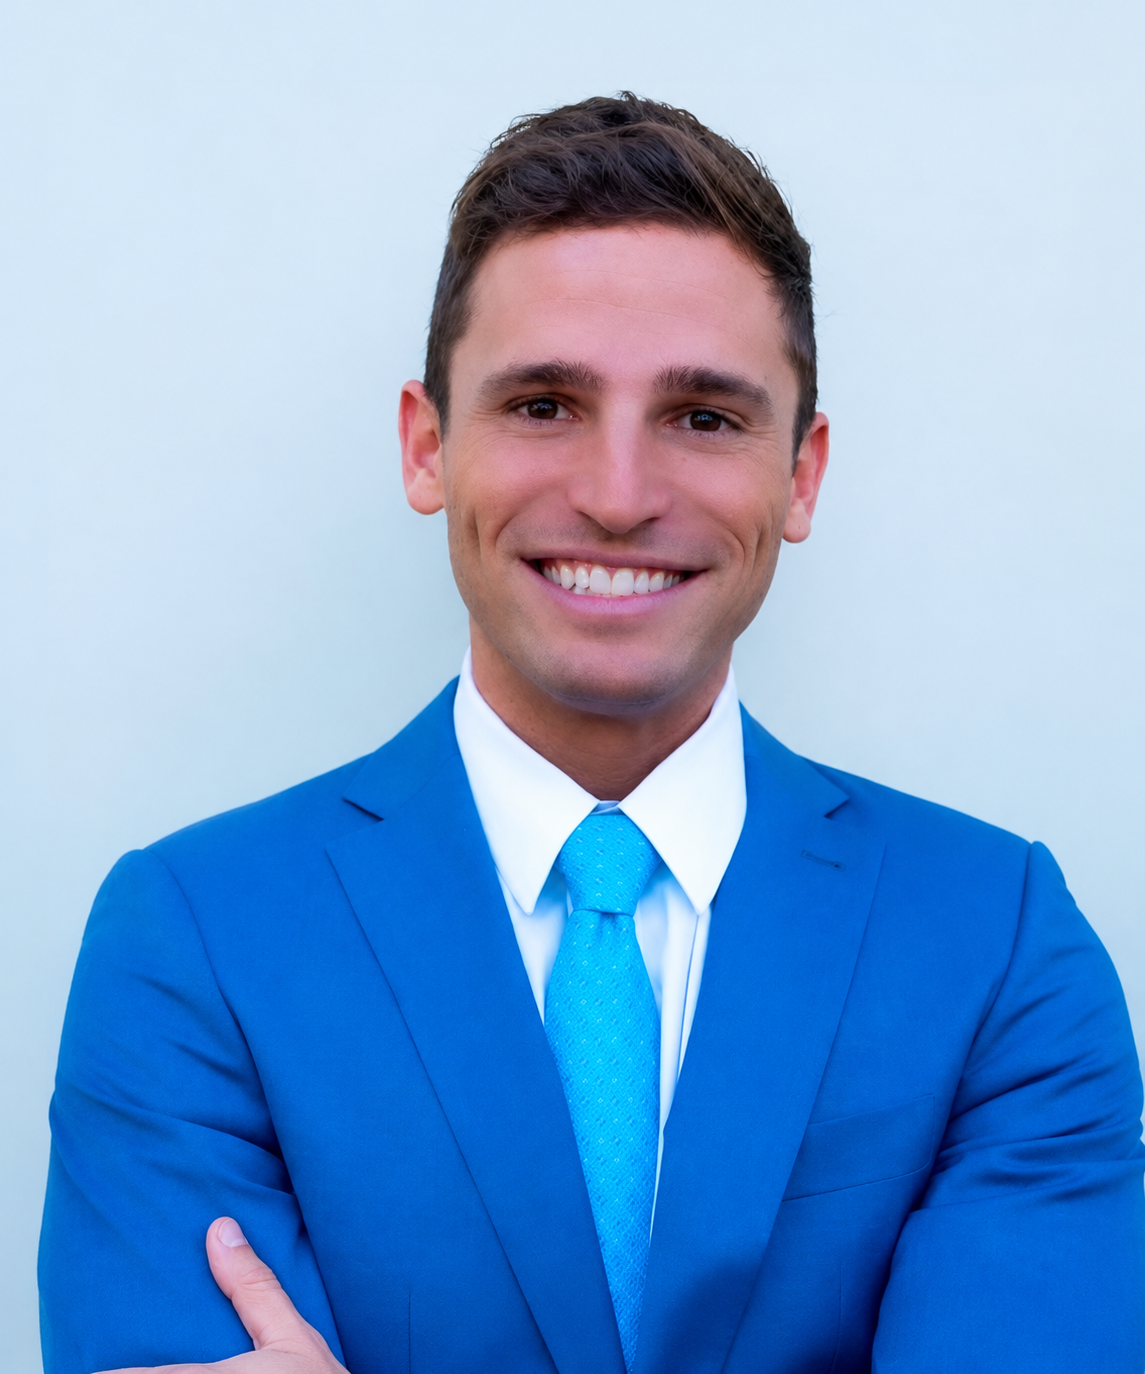
Loan Originator
Barrett Financial Group
A REAL PERSON. A CLEAR PLAN.
Work directly with Ethan—from the first conversation to the next step in your financing.
A cash-out refinance changes more than the amount of cash available. Ethan helps you review your current mortgage, the new financing, and the alternatives—so you can make a more informed decision.
GOOD QUESTIONS. STRAIGHT ANSWERS.
Have a scenario that doesn’t fit neatly into a box? That’s a good reason to start a conversation.
Ask Ethan directlyEligible borrowers may use UWM’s Conventional Cash-Out 90 program up to 89.99% LTV. This is a specific lender offering, not a statement that every conventional cash-out mortgage allows that amount.
No. The maximum is 89.99%, and it applies to the total new mortgage compared with the appraised home value. Your existing liens, closing costs and other adjustments are deducted to determine available cash.
The published Cash-Out 90 program does not require mortgage insurance. That does not mean there are no closing costs, or that this is the lowest-cost financing choice for every homeowner.
Refinancing pays off and replaces your current first mortgage. The new interest rate or payment could be higher, and the repayment period may be extended. Ask Ethan to compare keeping your existing loan and other potential equity-access options.
Potentially, subject to the lender’s requirements. Compare the total repayment cost, not only the monthly payment. Moving unsecured debt into a mortgage uses your home as collateral; failure to repay can put the home at risk. A longer repayment period can increase total interest.
No. The advertised Cash-Out 90 product is for eligible primary residences. Other property types need a separate program review and may have lower limits. Cash-Out 90 is not available in Texas.
This Cash-Out 90 inquiry form serves Arizona, California, Indiana and Ohio, subject to current lender requirements and state availability. The program is not available in Texas. Ethan’s general licensing disclosure includes Texas, but that license does not make Texas eligible for this program.
No. This contact request does not check your credit or authorize a credit report. A formal application and any separate credit authorization take place through Barrett’s application process.
Start with your contact details and your general goal. Do not include Social Security numbers, account numbers, tax returns or financial documents here. Financial documents belong in the approved secure application process.
LET’S LOOK AT THE POSSIBILITIES
Let’s see whether a cash-out refinance makes sense for you.